
Does Homeowners Insurance Cover Slab Leak Damage in California?
A slab leak is stressful enough on its own. Then comes the second question: will homeowners insurance help pay for any of it? The honest answer is that it depends on your policy, how the damage happened, and what kind of damage you are claiming. This guide explains, in general terms, how insurers usually look at slab leak claims in California, what to document, and which questions to ask your insurer before you assume anything.
This is general information only, not insurance advice and not a promise about any policy. Policies vary a lot, even between neighbors with the same carrier. Your own policy wording is the document that matters.
What a Slab Leak Claim Usually Involves
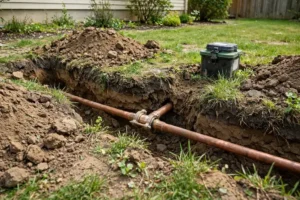
A slab leak means a water line under the concrete foundation of your home is leaking. The costs tend to fall into three buckets, and insurers often treat each bucket differently:
- Finding the leak. Detection work, such as acoustic listening or thermal imaging, to locate the leak under the slab.
- Repairing the pipe. The plumbing repair itself, whether that is a direct repair, a reroute, or another method your plumber recommends.
- Repairing the damage. Fixing what the water damaged, such as flooring, drywall, cabinets, or personal property.
Many homeowners are surprised to learn that a policy may help with one bucket and not another. For example, a policy might help with damage caused by the water while excluding the cost of repairing the worn pipe itself. That distinction is one of the first things to check in your policy.
What Policies Often Cover
Many standard homeowners policies cover sudden and accidental water damage. The key words are sudden and accidental. A pipe that bursts without warning and floods a room is a very different claim from a pipe that has been seeping slowly for months.
Damage that is often covered, depending on the policy, includes:
- Water damage to floors, walls, and belongings caused by a sudden pipe failure.
- The cost of drying out affected areas and preventing further damage after the failure is found.
- Additional living costs if the home becomes unlivable during repairs, where that coverage exists in the policy.
None of this is automatic. Coverage limits, deductibles, and exclusions all apply, and your insurer will want to see that the failure was sudden rather than gradual.
Why Slab Leaks Sit in a Gray Area
Slab leaks are tricky for claims because they often develop slowly. A pinhole leak under a slab can run for weeks before anyone notices a warm floor, a damp spot, or a higher water bill. When damage builds up gradually, insurers may argue that it falls under maintenance or wear and tear, which most policies exclude.
Other common exclusions to watch for include:
- Wear and tear, corrosion, and deterioration of old pipes over time.
- Damage from earth movement, settling, or shifting soil, which may need separate coverage in California.
- Damage that the homeowner knew about and did not act on for a long time.
- Mold or rot that developed because a leak went unaddressed, where the policy limits that coverage.
That is why early detection matters so much. The sooner a leak is found and documented, the easier it is to show that you acted promptly once the problem was known.
What to Do First When You Suspect a Slab Leak
If you suspect a slab leak, take these steps in order:
- Confirm the leak. A simple meter test can help: turn off all water in the home and watch the meter. If it still moves, water is going somewhere it should not. A plumber can then locate the leak with detection equipment.
- Stop further damage. Shut off water to the affected area if you can, move belongings away from damp spots, and keep the area as dry as possible.
- Document everything. Take dated photos and video of damp spots, flooring changes, meter readings, and any visible damage. Keep every invoice and report.
- Call your insurer promptly. Report the problem as soon as you know about it, and ask what documentation they need. Waiting weeks after discovery can hurt a claim.
- Get a written detection report. Ask your plumber for a written report describing what was found, where the leak is, and what repair is recommended. Insurers rely on this kind of record.
If you need help confirming a leak, our slab leak repair service covers detection and repair, and our post on slab leak warning signs explains the early symptoms to watch for.
Documentation That Strengthens a Claim
Insurers decide claims on evidence. The stronger your paper trail, the smoother the process tends to be. Keep:
- Dated photos and video from the day you first noticed the problem.
- Water bills showing a jump in usage, if you have them.
- Your plumber’s written detection report and repair estimate.
- Receipts for any emergency work, drying, or temporary repairs.
- Notes from every call with your insurer, including dates and names.
Do not throw away damaged flooring or materials until your insurer has had a chance to inspect them, unless they pose a safety problem. Insurers sometimes want to see the damage in person.
Questions to Ask Your Insurer
When you call, ask these questions and write down the answers:
- Does my policy cover water damage from a slab leak, and does it cover the pipe repair itself or only the resulting damage?
- What is my deductible for this kind of claim?
- Is detection work covered, or only the repair and restoration?
- Are there limits on flooring, mold remediation, or additional living costs?
- Do I need to use an insurer-approved contractor, or can I choose my own plumber?
- What is the deadline for filing, and what forms do you need?
These answers shape your next steps. If detection is not covered but damage repair is, for example, you will want to keep those costs separated on invoices.
The Bottom Line
Some slab leak costs may be covered by homeowners insurance, especially damage from a sudden failure, but the pipe repair itself and gradual damage are often excluded. Policies vary, exclusions matter, and documentation makes a real difference. Find the leak early, document everything, and talk to your insurer promptly rather than guessing about coverage.
Need Help in Fairfield?
If you suspect a slab leak in your Fairfield home, we can help confirm it and explain your repair options. We are open 09:00-17:00 daily. Call +1 707 574 9715 to book an inspection.